Day 36 of Sara Duterte’s impeachment trial: ?85 million in income, ?98 million in wealth, and the questions behind the figures
BlogWatch | October 9, 2026
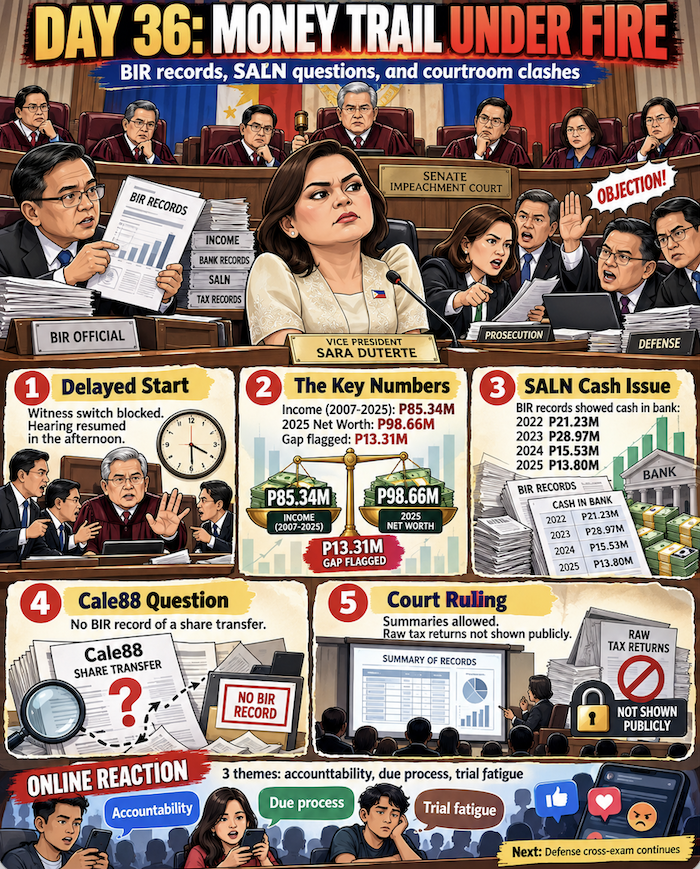
The Bureau of Internal Revenue (BIR) brought financial records to the Senate impeachment court on October 8, 2026. The figures immediately drew attention: Vice President Sara Duterte and her husband, lawyer Manases “Mans” Carpio, had a combined after-tax income of ?85.34 million from 2007 to 2025, while Duterte’s 2025 Statement of Assets, Liabilities, and Net Worth (SALN) showed ?98.66 million.
That is a difference of ?13.31 million, according to the House prosecution panel.
But can a difference between reported income and declared wealth establish unexplained wealth? And what happens when company shares disappear from an asset declaration without a corresponding transfer appearing in BIR records?
These were among the issues examined on Day 36 of Duterte’s impeachment trial, which focused on Article II, covering allegations of unexplained wealth, inaccurate asset declarations, and continuing business interests.
Five highlights from Day 36
1. A last-minute witness change delayed the hearing
Day 36 began with a dispute over the prosecution’s witness lineup.
Private prosecutor Erwin Matib, assigned to examine the BIR witness, reported being ill. The prosecution requested permission to present financial analyst and tax expert Alexander Cabrera first.
Defense lead counsel Sheila Sison objected. The defense had prepared for the scheduled BIR witness and argued that changing the order at the last minute would be unfair to Duterte.
The impeachment court suspended the morning proceedings. Matib eventually appeared in the afternoon and conducted the examination of BIR official Anne Loraine Garcia-Marquez.
The proceedings ended at 6:07 p.m., with defense counsel Kristine Ferrer having begun cross-examination.
The delay raised a practical concern about trial management. Both sides have a responsibility to prepare their witnesses and examinations. The prosecution must present its evidence properly, while the defense must have a fair opportunity to challenge it.
2. The BIR presented a ?13.31-million difference between income and net worth
Garcia-Marquez, chief of staff of the BIR commissioner, testified about income tax records covering Duterte and Carpio from 2007 to 2025.
Combined after-tax income
?85.34M
2007–2025
Declared net worth
?98.66M
2025 SALN
Difference identified by prosecution
?13.31M
Source: BIR testimony reported by GMA News and PhilSTAR Life. The difference is a comparison of two reported figures, not a finding of illicit wealth.
The prosecution argued that the couple’s reported earnings could not fully explain their declared net worth. The figures were presented as part of the allegations under Article II.
There is, however, an important accounting limitation.
An income tax return records income under applicable tax rules. A SALN reports assets, liabilities, and net worth at a particular date. They measure different things. Gifts, inheritances, certain capital gains, and changes in asset values may affect wealth without appearing as regular taxable income.
The prosecution therefore needs to establish the source and treatment of the assets, rather than rely on the difference alone.
3. BIR found no records of the reported transfer of Cale88 shares
Another significant disclosure involved Cale88 Foods Corporation, a company previously listed among Carpio’s business interests.
Garcia-Marquez testified that BIR database searches found no records documenting the sale, transfer, or other disposition of Carpio’s shares in Cale88. The agency also found no corresponding records of tax assessments or payments associated with such a transaction.
Cale88 had appeared in earlier asset declarations but was no longer listed in the couple’s joint 2025 SALN.
The company had also come under scrutiny over China- and Hong Kong-linked remittances. Reuters reported on October 6 that the National Security Council was examining concerns arising from these transactions, which banks had flagged to the Anti-Money Laundering Council.
The absence of transfer records does not, by itself, establish that Carpio retained ownership or that an unlawful transaction occurred. It does leave a question that requires documentary clarification: If the shares were transferred, where are the records establishing when and how that happened?
4. The prosecution questioned millions in cash holdings absent from separate SALN entries
The BIR witness also presented figures from the couple’s audited financial statements showing cash on hand and in banks over four years.
| Year | Cash on hand and in banks |
|---|---|
| 2022 | ?21.23 million |
| 2023 | ?28.97 million |
| 2024 | ?15.53 million |
| 2025 | ?13.80 million |
According to the House prosecution, Duterte’s SALNs did not separately identify these cash holdings.
House prosecution adviser Ace Barbers disputed the explanation that the amounts had been included under other personal properties. He alleged that the omissions amounted to deliberate concealment.
That remains the prosecution’s allegation, rather than an established finding of the impeachment court.
The figures must be reconciled with the actual SALN entries, including any assets grouped under broader categories. The defense must also have the opportunity to challenge the prosecution’s interpretation.
For citizens, the issue is straightforward. Public officials are required to disclose their assets under Republic Act No. 6713. If millions of pesos are recorded in financial statements but cannot be identified in asset declarations, the public deserves an explanation supported by records.
5. Tax return disclosures brought privacy and constitutional questions before the court
Defense lawyer Kristine Ferrer objected to the public display of Duterte’s income tax returns, citing the Data Privacy Act and the confidentiality of tax information.
The impeachment court allowed summaries and comparison tables prepared from the BIR records to be shown publicly, while restricting the display of the original tax documents.
Another issue concerned a BIR Form 2316 associated with compensation from the Davao City government. The prosecution questioned whether Duterte had received additional government compensation while serving as vice president.
Article VII, Section 6 of the Constitution prohibits the president and vice president from receiving other emoluments during their tenure. However, an October 9 ABS-CBN report identified the compensation in Duterte’s 2023 tax filing as pay from her time as mayor in 2022. The filing year alone cannot establish that she received prohibited compensation for work performed while vice president.
The hearing also exposed the limits of interpreting tax forms without their complete context.
The Philippine Star reported that blank entries for non-taxable income or income subject to final tax did not necessarily mean no such income existed.
These distinctions matter when the Senate evaluates the prosecution’s calculations and the defense’s explanations.
Netizen reactions: The money trail and the trial delays
Discussions around Day 36 reflected public interest in the financial evidence as well as frustration over courtroom delays.
A Reddit discussion thread devoted to Day 36 included viewers trying to catch up with earlier sessions and following the proceedings as they happened.
One participant commented:
“Catching up pa lang ako sa day 35, meron na agad for today’s vidyow”
Another wrote:
“agahan natin kasi busy ako bukas lol”
Both comments appeared in the Day 36 megathread on r/Philippines.These comments show viewers following the hearings closely, although they are not evidence of wider public sentiment.
The research supplied for this article also grouped reactions into those demanding financial accountability, those defending due process, and those frustrated by procedural delays. However, I could not independently authenticate the individual quotations in those groups. They have therefore been excluded.
The public discussion needs to distinguish between what witnesses testified, what prosecutors alleged, and what the impeachment court has actually established. A financial discrepancy can warrant further examination without automatically proving corruption.
What happens next?
The defense began cross-examining Garcia-Marquez on October 8, with questioning scheduled to continue on October 9.
The House prosecution also moved to narrow its case. ABS-CBN reported on October 9 that prosecutors had decided to drop the bribery article, allowing them to concentrate on other allegations.
For Article II, several matters remain to be resolved:
-
Whether the ?13.31-million difference can be explained by lawful sources of wealth and accounting treatment.
-
Whether the cash balances in the audited financial statements were properly reflected in Duterte’s SALNs.
-
Whether Carpio’s Cale88 shares were transferred, and what records support that transaction.
-
Whether the defense can reconcile the questioned documents with the prosecution’s evidence.
Conclusion: Follow the records, not the accusations
Day 36 gave the public specific figures and documents to examine. The ?85.34-million income figure and the ?98.66-million net worth comparison are now part of the public discussion. So are the cash balances and the missing BIR records relating to Cale88 shares.
The figures call for explanations. The defense has the right to test them, and the prosecution has the responsibility to prove its allegations.
As citizens, we can follow the original testimony, compare the financial records, and resist treating either an accusation or a denial as a final answer.
The most useful documents to watch in the next hearing are the SALN entries, the BIR summaries, and any records showing what happened to Carpio’s Cale88 shares.
The evidence should establish what happened to the assets. Political loyalties cannot settle that question.
Day 35 Sara Duterte Impeachment Trial : The ?96 Million Question and the Missing Signatures in Sara Duterte’s Impeachment Trial
Day 20 Sara Duterte Impeachment Trial: Certificates without a money trail
Day 23 Sara Duterte Impeachment Trial : The trial turns to Sara Duterte
About The Author

Noemi Lardizabal-Dado
Noemi Lardizabal-Dado is a content strategist with over 19 years of experience in blogging, content management, citizen advocacy, and media literacy, and over 30 years in web development. Otherwise known as @MomBlogger on social media, she believes in making a difference in the lives of her children by advocating for social change that benefits the greater good. She is a co-founder and a member of the editorial board of Blog Watch . She is a resource speaker on media literacy, social media, blogging, digital citizenship, good governance, transparency, parenting, women’s rights, wellness, and cyber safety. Her personal blogs such as aboutmyrecovery.com (parenting) , pinoyfoodblog.com (recipes), techiegadgets.com (gadgets) and benguetarabica.coffee keep her busy outside of Blog Watch. Disclosure: I am an advocate. I am NOT neutral. I will NOT give social media mileage to members of political clans, epal, a previous candidate for the same position and those I believe are a waste of taxpayers' money. I do not support or belong to any political party. I was part of accredited media covering the Office of the Vice President and Leni Robredo as she ran as a presidential aspirant in the 2022 National and local elections. On August 5, 2021, YouTube announced that I was selected as one of 50 Program participants of its Creator Program for Independent Journalists She was a Senior Consultant for ALL media engagements for the PCOO-led Committee on Media Affairs & Strategic Communications (CMASC) under the ASEAN 2017 National Organizing Council from January 4 -July 5, 2017. Having been an ASEAN advocate since 2011, she has written extensively about the benefits of the ASEAN community and as a region of opportunities on Blog Watch and aboutmyrecovery.com. Organization affiliation includes Consortium on Democracy and Disinformation Updated June 6, 2022